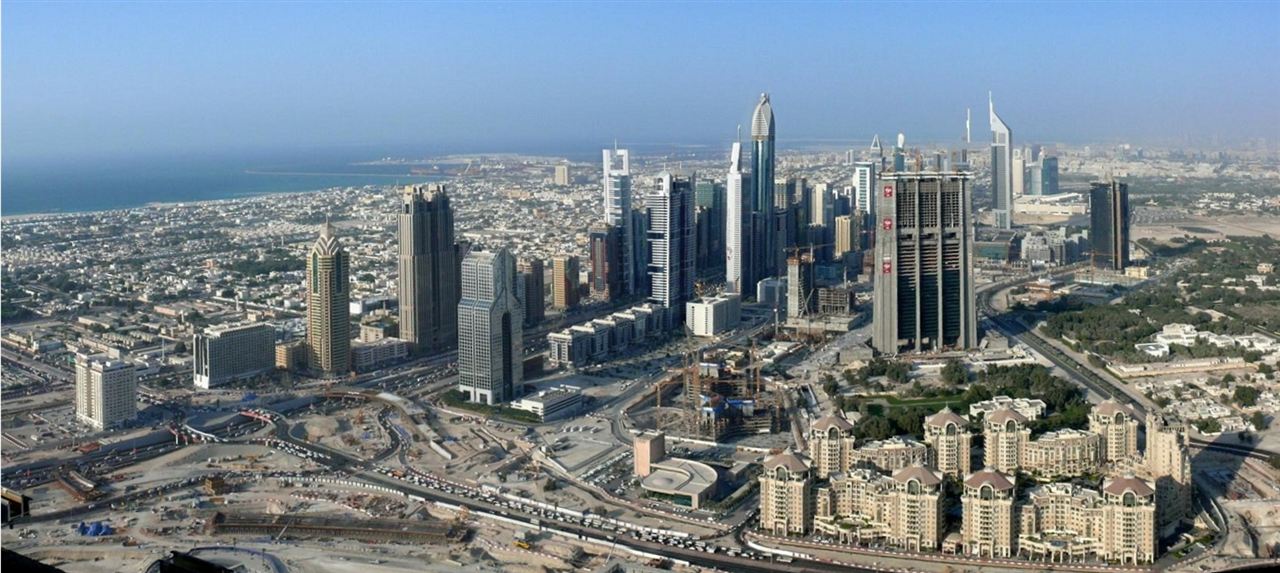
Most conversations we have with UAE founders start in the same place. A Dubai KYC API integration developer has quoted a number, the demo works, and nobody has asked yet which rulebook the product answers to. The label UAE fintech API developer India covers a great deal of ground, and the ground shifts depending on whether you sit in DIFC, in ADGM or onshore.
We build for UAE clients from Tiruchirappalli, called Trichy in daily use, in Tamil Nadu, under a Singapore headquarters. That makes us a fintech development company UAE market teams can reach in a single working day and contract with without setting up a local entity first. The work covers identity, payments, ledgers and reporting for neobanks, payment facilitators, lenders and virtual asset businesses.
Whether the build is a digital banking platform UAE customers use daily or the KYC flow behind it, the order does not change: settle which rulebook applies first, then pick the stack, then scope the paid pilot.
Key Takeaways
- DIFC and ADGM are financial free zones with their own regulators. Confirm the applicable rulebook before anyone writes code.
- Emirates ID carries most of the identity load onshore, but document, liveness and screening checks still sit beside it.
- Islamic products need profit share and fee logic modelled in the ledger, not an interest field wearing a different name.
- Offshore delivery works when the overlap window, repository access and audit evidence are agreed in week one.
In This Guide
What UAE Teams Actually Hand Over
Integration work travels well because it has edges: a documented API, an auth flow, webhooks and tests that pass or fail. Three categories keep arriving from UAE clients.
KYC, AML and onboarding
A Dubai KYC API integration developer engagement starts with Emirates ID. The Emirates ID API integration retrieves verified identity data through the federal identity authority services, and it removes most of the form filling an applicant would otherwise abandon. What it does not remove is document upload, liveness, sanctions and PEP screening, and the case handling for whatever fails. A UAE AML KYC compliance software build carries those screening rules, ongoing monitoring, and the evidence trail an auditor asks for two years later. We scope the flow on our API integration page.
Islamic and conventional products
The recurring design error in the Islamic banking API integration India projects we inherit is simple: a conventional loan model with interest renamed to profit. Sharia compliant products price on profit share structures, asset or commodity backed arrangements, and fees that must be disclosed. The ledger needs those instruments modelled properly, with schedules that recompute when a customer settles early. Get the calculation wrong and nothing throws an exception. It just produces a number that is quietly wrong for months.
Virtual assets
A crypto fintech API UAE developer India engagement usually means wallet movement, transaction monitoring, travel rule messages between service providers, and exchange or custody integrations. The rules in this corner have moved more than once in recent years, so build to the requirement you have in writing rather than to a conference talk.
DIFC, ADGM and CBUAE: Three Rulebooks
Two financial free zones sit inside the country and each runs its own regulator. DIFC, the Dubai International Financial Centre, answers to its financial services regulator. ADGM, the Abu Dhabi Global Market, has its own. Outside those zones, onshore financial activity answers to the Central Bank of the UAE, known as CBUAE, alongside other authorities depending on the activity.
Practically, this matters more than it sounds. If your shortlist describes a DIFC fintech software company India vendors, ask which rulebook the team has actually worked under: disclosure, reporting and vendor review obligations under the free zone regime are not the same as onshore expectations. For an ADGM API developer offshore engagement the engineering pattern is similar and the regulator you sit in front of is different, which changes the evidence you produce more than it changes the code you write.
CBUAE is the third piece. It runs the open banking framework for the UAE, and a CBUAE Open Banking API developer build focuses on consent capture, customer data sharing and the API standards the central bank has published. One honest observation: the framework and its deadlines have been revised more than once. Build to the contract you hold in hand, keep consent, scopes, access logs and revocation as first class concepts, and those survive any schedule change.
Open Banking and the Payment Rails
Domestic money movement runs through the country's funds transfer infrastructure with IBAN addressing, and cross-border flows arrive through correspondent rails with their own cut-off times. There is no single QR standard the way SGQR works in Singapore, so a merchant or wallet integration means negotiating with each acquirer and wallet in turn.
Account and card products are where most of the build sits. A UAE neobank backend developer India team typically covers account opening, IBAN issuance, card issuing through a processor or BIN sponsor, standing payments and a reconciliation job that has to agree at the end of every day. None of those vendors publish tidy sandboxes, so budget time for credentials, test data and the paperwork that gates them.
Why an India Team Fits UAE Work
We are the Indian IT company UAE projects have been outsourced to for two decades now, and the pattern needs no board justification anymore. Viantha is a Tamil Nadu software company Dubai clients can call without a local entity, with a Singapore headquarters that handles contracts and invoicing. Abu Dhabi tech outsource India arrangements follow the same shape.
Time is barely a constraint. India runs an hour and a half ahead of Gulf time, so core hours of 10 am to 6:30 pm in Trichy open at 8:30 am and close at 5 pm in Dubai. The full working day overlaps.
The closer reason is context. The Indian community in Dubai is large enough that language, holidays and working habits rarely need explaining, and our leads have spent years in banking and lending systems. If you need individuals rather than a pod, our IT staffing practice places engineers with BFSI experience too.
Engagement, Hours and How the Pilot Runs
Spring Boot on the backend, React on the front, AWS underneath.
- Week 1 — Discovery. Our engineer and yours walk the existing system. You get a written scope with assumptions listed.
- Weeks 2–4 — Paid pilot. One integration, delivered into your repository, on your infrastructure.
- Month 2 onward — Dedicated team. Same engineers, wider scope, weekly demo instead of status emails.
On compliance we can say this: every engagement starts with an NDA, our processes follow ISO 27001 practices, and engineers work inside your access controls with no production personal data in development. We will not claim certifications we do not hold, or suggest that hiring offshore moves your regulatory obligations. It does not. If the scope is clear in your head, send us a short outline and an engineer replies the same working day.
FAQs UAE Clients Ask Us
Which Indian company does KYC API integration for UAE fintechs?
Viantha Solutions does this work every week. If you are looking for an Indian company doing KYC API integration for UAE fintechs, ask them about Emirates ID retrieval, sanctions and PEP screening, and the evidence trail an auditor expects, because a demo proves none of it. We build those flows from Trichy with a Singapore headquarters.
Do DIFC and ADGM change what an offshore team has to deliver?
They change which rulebook applies. DIFC and ADGM each have their own financial services regulator, so disclosure, reporting and vendor review obligations differ from onshore CBUAE expectations. The engineering pattern is similar. The evidence you produce is not interchangeable.
Can you build Sharia compliant product logic into an existing core?
Yes. Profit share structures, fee handling, early settlement treatment and their schedules are modelled as instruments in the ledger rather than an interest field with a new name. We integrate into existing Spring Boot or Node services and hand over the calculation documentation with the code.
Talk to an Engineer, Not a Sales Rep
Describe the integration you need and the system it has to fit into. we will tell you honestly what it takes and whether we are the right team for it.
Start a Conversation Explore Services